 Sign up with Google
 Sign in with Zoho
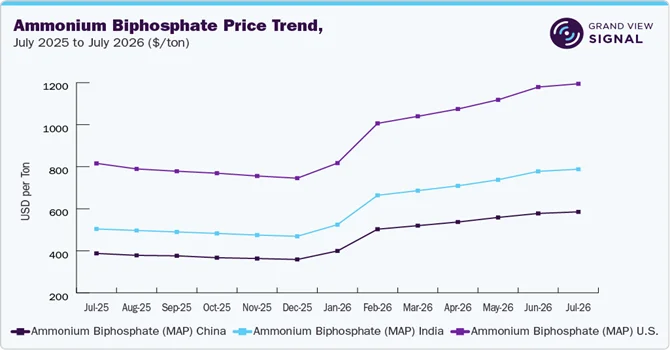
As the foundation of global food security, mineral fertilizers are indispensable to modern agricultural productivity, directly determining crop yields and farm economics worldwide. However, because fertilizer production relies heavily on concentrated energy sources and strategic mineral deposits, the sector remains uniquely vulnerable to geopolitical shocks. Recent conflict dynamics involving Iran, a critical exporter of urea and key regional energy supplier, have severely disrupted trade routes through the Strait of Hormuz, driving up shipping risk premiums and tightening global nitrogen and raw material availability.
Amid this turbulent macro backdrop, specialty and high-analysis products have seen rapid strategic realignments; most notably, ammonium biphosphate MAP in the U.S. has experienced a stunning growth of 46.4% over the past year, as buyers aggressively seek concentrated, reliable phosphate sources to hedge against volatile input costs.
To navigate these volatile commodity dynamics, leaders rely on Grand View Signal, a SaaS-based platform that delivers real-time pricing intelligence, trade flow tracking, and forward-looking market analytics to optimize global sourcing and risk management strategies.
China’s Quiet Market vs. Rising Global Prices
China’s domestic urea market remained quiet throughout July, with local supplies proving more than adequate to meet immediate spot demand. However, international nitrogen markets moved in the opposite direction, driven by tightening seaborne availability and rising freight rates.
This regional disconnect carries significant weight for the global agricultural sector. Nitrogen is the single largest fertilizer consumed by mass globally, with just three staple crops accounting for over 50% of total demand: maize/corn (20%), wheat (18%), and rice (16%). As fertilizer historically represents a massive share of total crop input costs, averaging 21% for corn production and 19% for wheat, even modest shifts in landed nitrogen prices directly alter farm operating economics.
When international seaborne replacement costs rise, import-dependent regions are forced to absorb higher freight rates, elevated insurance premiums, and alternative sourcing markups. For growers already navigating volatile grain markets, these compounding input expenses quickly erode operating margins, making disciplined procurement strategies essential for mitigating supply chain exposure.
How Shipping Constraints and Energy Costs Affected Supply in Middle East
The Middle East remains a vital exporter of urea, ammonia, and essential fertilizer raw materials. As a result, supply-chain interruptions in the region quickly impacted global availability, and marked a month-on-month decline of 1.4%.
- Ammonia Restrictions: Limited export shipments from the Middle East drove up international replacement costs across several nitrogen products.
- Energy Costs: Rising European natural gas prices increased the underlying cost of producing nitrogen fertilizers in Western Europe.
- Logistics Challenges: UAE-based producers encountered shipping and logistical constraints. However, their diversified manufacturing locations helped prevent major order cancellations.
Faced with these pressures, international buyers adjusted by diversifying their supplier bases and holding larger inventory buffers whenever financially possible. Nitrogen and phosphate products felt these pressures most directly, while potash remained largely shielded from natural gas cost spikes.
India’s Strategic Balance During Kharif Season
India’s agricultural sector created substantial demand in July due to ongoing Kharif crop cultivation. Farmers actively applied urea, phosphate, and potash across major agricultural belts. To keep local prices stable and prevent panic buying, the Indian government carefully managed its national inventory.
A combination of active domestic manufacturing, international urea procurement tenders, monthly distribution plans, and existing long-term import agreements kept local supply ahead of farmer demand. Government agencies actively monitored movement across states to redirect fertilizers wherever field activity peaked. By managing its national inventory so deliberately, India supported steady global trade volumes without creating sudden, aggressive buying sprees that could have driven international prices higher.
Phosphate Supply Constraints and Strategic Partnerships
Phosphate fertilizers remained vulnerable to raw material bottlenecks in July, particularly regarding access to sulfur, ammonia, phosphate rock, and phosphoric acid. Disruptions across Middle Eastern trade corridors raised shipping risks and landed costs for input materials. At the same time, tight export controls on Chinese phosphate limited options for global buyers.
Monoammonium phosphate (MAP) prices inside China remained steady, but this stability did not reflect the higher replacement costs faced by overseas importers. Fertilizer producers with fully integrated phosphate rock assets held a distinct advantage, especially those capable of securing alternative sulfur and ammonia streams.
On a strategic level, Morocco expanded a major phosphate partnership in July, strengthening long-term global production capacity. Koch Ag & Energy Solutions and OCP Nutricrops have signed an agreement for Koch to acquire a 50% stake in Jorf Fertilizers Company I (JFC I). The 50-50 joint venture in Morocco will strengthen global supply chains and enhance phosphate fertilizer availability, particularly for North American farmers.
Why Potash Remained Stable Despite Global Pressures
Unlike the volatile nitrogen sector, potash markets experienced a far more stable month. In India, muriate of potash (MOP) inventories comfortably exceeded seasonal requirement forecasts, by marking Y-O-Y growth of 7.6%, taking away any urgency for sudden spot-market imports. China’s monitored potassium market similarly saw minimal price movement, confirming that supply was sufficient to meet current demand.
Agricultural buyers continued to time their potash purchases based on crop profitability, existing inventory, and scheduled field application dates. Meanwhile, specialty products like sulfate of potash (SOP) and potassium nitrate followed smaller, highly selective purchasing cycles tailored to high-value, chloride-sensitive crops. High freight rates still added to delivered costs, but strong stock levels and deliberate buyer patience kept domestic potash prices steady throughout the month.
Make Better Commodity Decisions with Signal
Navigating shifting fertilizer prices, trade restrictions, and supply disruptions requires reliable intelligence. Signal provides industry leaders with clarity across global agricultural inputs through tailored research and analytical tools.
Grand View Signal’s core offerings include:
- Real-Time Price Benchmarking: Granular price tracking across major global fertilizer hubs to track replacement costs and market shifts.
- Global Trade Flow Tracking: Daily monitoring of ocean freight rates, shipping vessel movements, and regional supply-chain bottlenecks.
- Custom Supply & Demand Analytics: Forward-looking forecasting dashboards for nitrogen, phosphate, and potash markets.
- Policy and Export Tracking: Up-to-date reporting on trade regulations, government tenders, and export restrictions worldwide.
- Strategic Advisory Services: Tailored consulting services for producers, traders, and institutional investors managing commodity risk.